
Fidelity Bank Ghana has called for increased mobilisation of domestic capital, investment in technology and targeted policy interventions to accelerate industrialisation and translate Ghana’s economic recovery into sustainable growth.
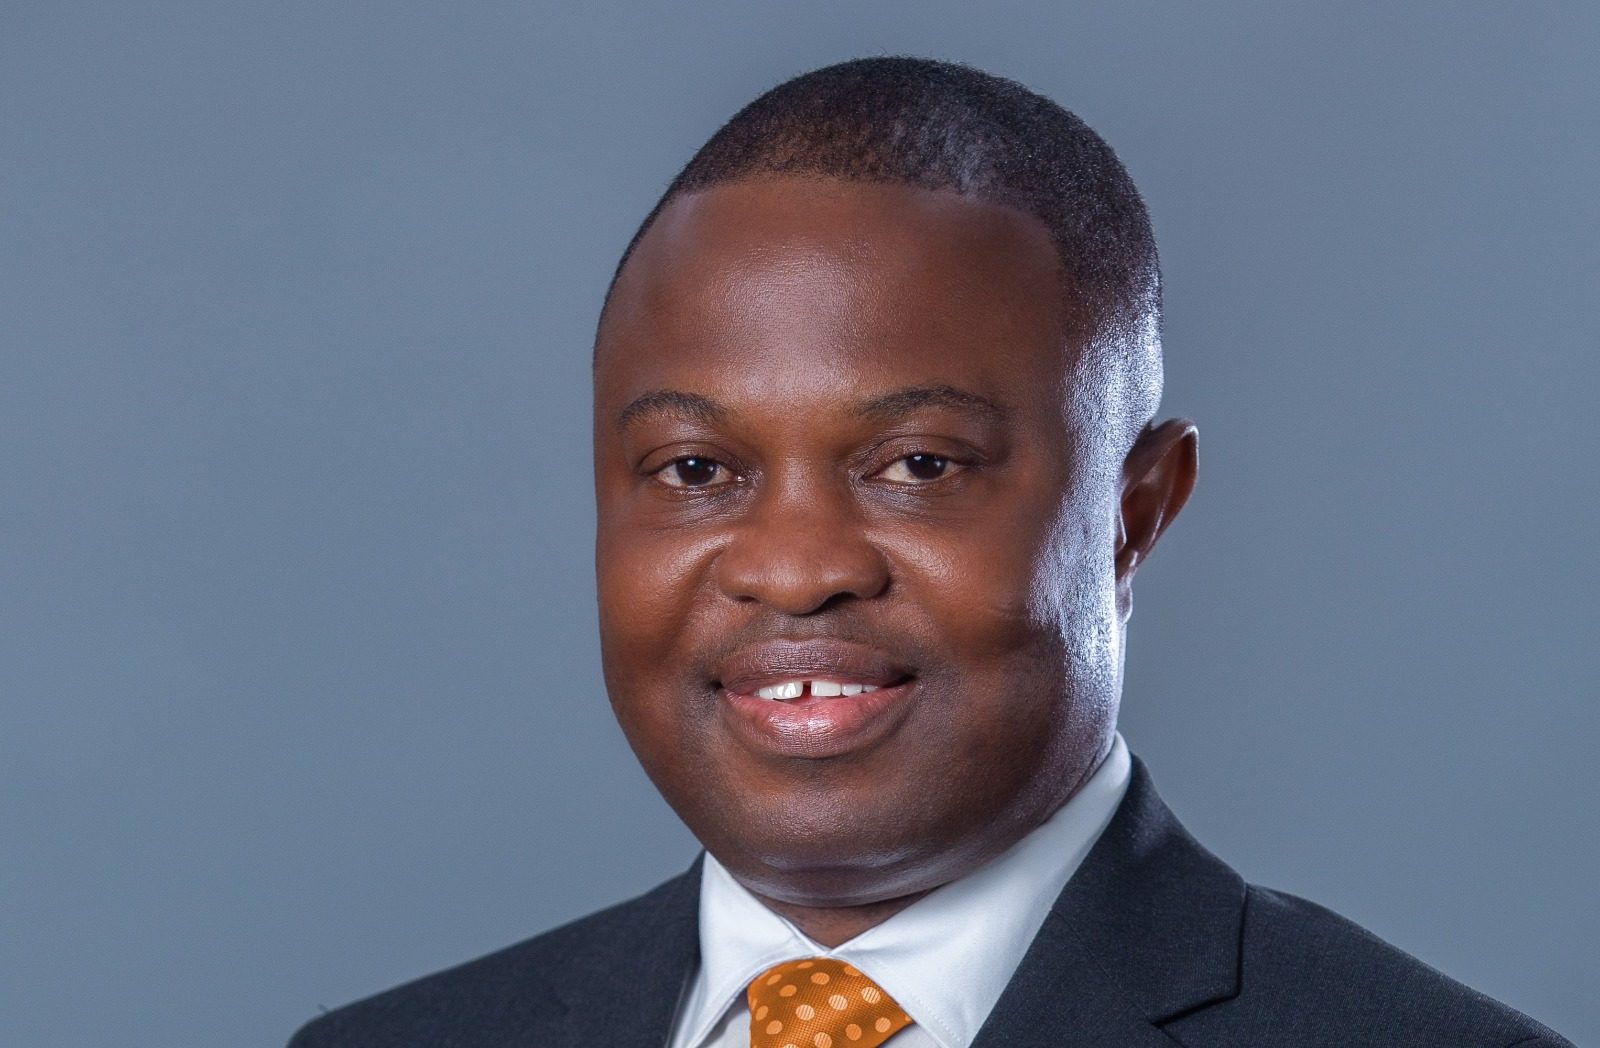
The call was made by Atta Yeboah Gyan, Deputy Managing Director, Operations and Support Functions, Fidelity Bank Ghana, at the 2026 Ghana Economic Forum, where the Bank served as Lead Sponsor. The Forum was themed “From Stabilisation to Scale: Mobilising Capital, Technology, and Policy for Ghana’s Next Industrial Wave.”
Addressing business leaders, policymakers, investors and other stakeholders, he acknowledged Ghana’s progress in restoring macroeconomic stability but stressed that the next challenge was converting those gains into stronger businesses, increased production, jobs and sustainable growth.
“Stabilisation is not the final destination. The real test is whether we can turn that stability into investment, stronger businesses, increased production, more jobs and sustainable growth,” he said.
Atta Yeboah Gyan pointed to Ghana’s growing dependence on gold exports as a vulnerability that must be addressed. In 2025, gold accounted for approximately US$20 billion of the country’s US$31.1 billion merchandise exports, representing almost two-thirds of total export earnings. By August 2026, its share had risen to 66%.
While acknowledging gold’s importance to the economy, he argued that Ghana must leverage its natural resource earnings to build a more diversified productive economy, with greater emphasis on manufacturing, local processing and value addition.
“The concern is that too much of our external stability now depends on a single commodity whose price is determined beyond our borders,” he noted.
Drawing lessons from Malaysia’s cocoa-processing industry and Switzerland’s chocolate industry, Mr. Gyan highlighted the importance of moving beyond raw material production to capture greater value through processing, branding, quality standards and global distribution. He also identified the African Continental Free Trade Area (AfCFTA) as an opportunity for Ghanaian manufacturers to access a continental market of more than one billion consumers.
On financing, Mr. Gyan said Ghana had significant domestic resources that could support industrial expansion, citing pension funds holding more than GH¢100 billion and growing insurance investments.
He called for investment instruments that better reflect the needs of industry, including longer-term bonds for factories and financing structures that align with agricultural production cycles.
He also highlighted Fidelity Bank’s ambition to list on the Ghana Stock Exchange, describing it as part of the Bank’s conviction in developing Ghana’s capital market.
“If Ghana’s savings are to fund Ghana’s industry, then Ghanaian companies, our own included, must be ready to open our books, meet the market’s standards and earn that capital,” he said.
Sharing Fidelity Bank’s experience with technology, Mr. Gyan noted that more than 90% of the Bank’s transactions now take place through digital channels. Its automation programme saves more than 18,000 staff hours annually and has delivered approximately GH¢5 million in measured benefits. Service level adherence also improved from 84% to 97% within 12 months.
He stressed that technology investments must deliver measurable improvements in productivity and service, supported by clean data, reliable digital processes and effective systems.
On policy, he emphasised the importance of reliable and affordable electricity to industrial expansion, calling for collaboration between government, financial institutions and private investors to develop sustainable energy solutions.
He also highlighted the need to reduce agricultural financing risks through partnerships among government, banks and development partners, ensuring that financing reaches the entire value chain, from farmers and aggregators to processors.
Concluding, Mr.Gyan said Ghana’s next phase of growth required collective responsibility from government, investors, businesses and financial institutions.
“Stabilisation has largely been the work of government and the central bank. They have done their part. Scale is everyone’s work,” he said.
He reaffirmed Fidelity Bank’s commitment to supporting Ghana’s economic development as a lender and partner to businesses, and to contributing to a stronger financial system that can finance the country’s next phase of industrial growth.